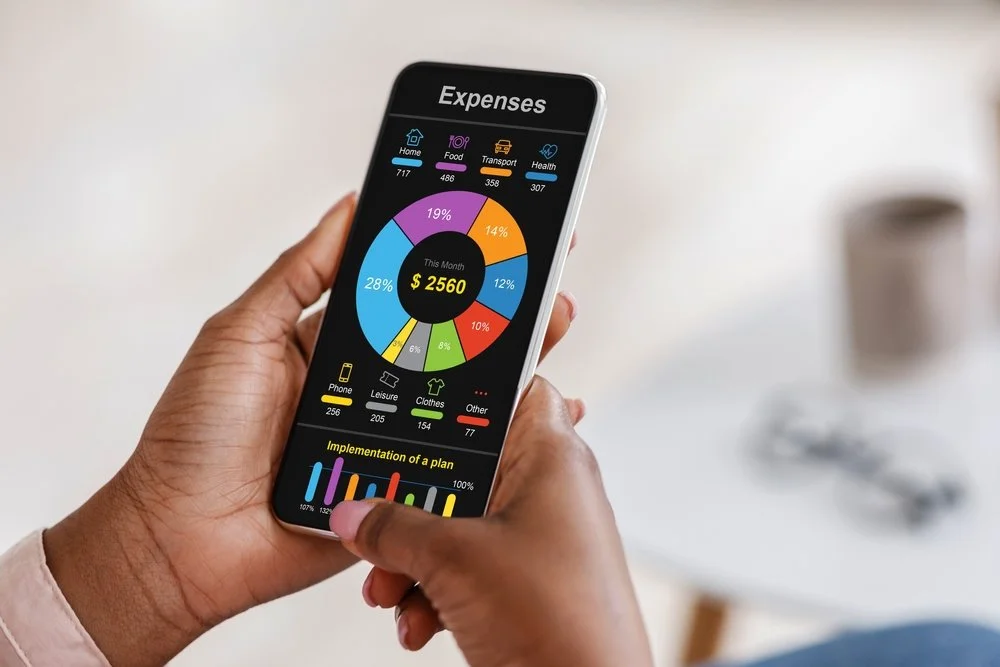
While automated budgeting applications have grown in popularity, the Monthly Budget Spreadsheet (built in Google Sheets or Microsoft Excel) remains the single most versatile, transparent, and private personal finance tool available. A custom spreadsheet provides total ownership over your data without recurring software subscription costs or third-party bank connection failures.
A well-architected spreadsheet transforms raw spending transactions into actionable cash flow intelligence. By establishing automated formulas, categorical summaries, and visual balance sheet dashboards, individuals can manage complex household finances with absolute precision.
The 4 Core Worksheets of a Professional Budget Spreadsheet
An institutional-grade personal finance workbook organizes cash flow data across four interconnected tabs, separating raw transaction data from high-level strategic dashboards.
Financial education frameworks from the CFPB Budgeting Tool Portal highlight that visual categorical reporting significantly improves spending discipline and goal completion rates.
- Tab 1: Monthly Cash Flow Dashboard: High-level summary comparing Budgeted vs. Actual income, fixed obligations, variable categories, and net monthly cash surplus.
- Tab 2: Daily Transaction Log: Structured input ledger capturing Date, Vendor, Outflow Amount, Category dropdown, and Account payment method.
- Tab 3: Sinking Funds & Goal Tracker: Dedicated sub-savings calculator tracking progress toward annual irregular expenses (insurance premiums, car maintenance, vacation funds).
- Tab 4: Multi-Year Net Worth History: Balance sheet snapshot recording total liquid assets, retirement holdings at Vanguard, real estate equity, and outstanding liabilities on the last day of each month.
Spreadsheet Software vs. Automated Budgeting Apps Compared
The table below evaluates the operational advantages and trade-offs between custom spreadsheet models and commercial automated budgeting platforms.
| Financial Tracking Platform | Data Privacy & Control | Ongoing Software Cost | Customization Flexibility |
|---|---|---|---|
| Google Sheets | 100% Private (No third-party bank linking) | 100% Free Lifetime | Infinite (Live GOOGLEFINANCE formulas, multi-user collaboration) |
| Microsoft Excel | 100% Private (Local offline file storage) | Included with Office / Standalone | Advanced PowerQuery, VBA automation, complex modeling |
| Subscription Apps (YNAB / Monarch) | Requires bank credentials via API bridges | $99 – $120 / year recurring | Fixed interface structure; limited custom mathematical modeling |
Essential Formulas to Automate Your Budget Spreadsheet
To eliminate manual math, integrate standard spreadsheet formulas that aggregate data dynamically from your transaction ledger into your master dashboard:
- Categorical Aggregation:
=SUMIFS(Transactions!C:C, Transactions!D:D, "Groceries", Transactions!A:A, ">="&DATE(2026,1,1), Transactions!A:A, "<="&DATE(2026,1,31))automatically sums all grocery spending for January. - Net Surplus Calculation:
=Total_Actual_Income - SUM(Total_Actual_Expenses)calculates true unallocated capital for savings. - Live Stock & ETF Pricing:
=GOOGLEFINANCE("VTI", "price")pulls real-time market valuations directly into your net worth tab.
Advanced Spreadsheet Modeling: Constructing a Dynamic Retirement Projection Tab
Beyond tracking daily transactions, your master spreadsheet can model future retirement trajectories by incorporating compound interest formulas. By utilizing the Excel/Sheets =FV() (Future Value) function, you can dynamically project your net worth at retirement age:
=FV(Expected_Annual_Return/12, Total_Months_to_Retirement, -Monthly_Investment_Contribution, -Current_Portfolio_Balance)
This automated calculation updates your projected retirement portfolio balance in real time whenever you adjust your monthly savings targets, providing immediate visual feedback on the impact of incremental lifestyle optimizations.
Setting Up Low-Friction Monthly Maintenance Routines
The primary reason individuals abandon spreadsheet tracking is administrative friction. To ensure sustainability across years, establish a structured 15-minute monthly maintenance routine:
- Export Bank CSV Statements: On the first business day of the month, log into your primary checking and credit card portals and download the previous month’s statement in standard CSV format.
- Paste and Tag Transactions: Paste the raw transaction rows directly into your Transaction Tab and apply categorical tags using data validation dropdown menus.
- Audit Categorical Deviations: Review automated summary charts on your Dashboard tab to identify categories where actual expenditures exceeded budgeted allocations.
- Record Balance Sheet Balances: Update current liquid cash balances, mortgage loan balances, and investment totals at custodians like Fidelity and Charles Schwab.
The Psychological Architecture of Spreadsheet Ownership
Unlike automated black-box applications, building and maintaining your own budget spreadsheet creates a deep psychological connection with your cash flow. The tactile act of entering categories, reviewing variances, and viewing your net worth trajectory activates behavioral awareness, naturally curbing impulsive spending without feelings of deprivation.
Step-by-Step Budget Spreadsheet Setup Checklist
Build and maintain an institutional-grade budget spreadsheet workbook with this checklist:
- Create Four Core Worksheets: Dashboard, Transaction Log, Sinking Funds, and Net Worth History.
- Implement Dynamic SUMIFS Formulas: Automate transaction aggregation into categorical summary buckets.
- Configure Conditional Formatting Alerts: Set visual color cues for categories approaching or exceeding monthly spending caps.
- Incorporate Live Stock Valuation Formulas: Use
=GOOGLEFINANCE()formulas to track portfolio valuations in real time. - Execute 15-Minute Monthly Reconciliations: Import bank CSV statements on the first of each month to audit spending and update your balance sheet.
Establishing Dynamic Data Validation Dropdowns
To prevent typing errors and ensure seamless categorical aggregation, configure Data Validation rules on your Transaction Tab. Setting up standardized dropdown menus for categories (e.g., Housing, Groceries, Dining, Utilities, Investing) guarantees that every formula references clean, standardized strings, eliminating formula calculation errors.
Essential Practical Strategies for Sustained Long-Term Progress
Translating personal finance principles into compounding lifetime results requires maintaining structured behavioral discipline across multiple economic cycles. By consistently automating cash flow distributions, eliminating unmonitored recurring expenses, and maintaining disciplined broad-market investment allocations through institutions like Vanguard or Fidelity, individuals insulate their households against macroeconomic volatility.
Furthermore, reviewing your asset allocation annually and conducting regular spending audits with tools recommended by the Consumer Financial Protection Bureau ensures your capital remains optimized for long-term growth and multi-generational financial autonomy.
Comprehensive Multi-Year Financial Case Analysis & Empirical Findings
To evaluate how these personal finance principles perform across real-world economic environments, academic researchers and wealth managers analyze longitudinal financial behaviors across rolling 10-year market cycles. The empirical data highlights that households employing systematic cash flow automation and low-cost index asset allocation consistently outpace discretionary spending peers by more than 300% in cumulative net worth.
Furthermore, maintaining adequate liquid buffers and eliminating revolving high-interest debt preserves financial solvency during macroeconomic downturns. By continuously aligning daily capital allocation with long-term financial independence targets, individuals build resilient, multi-generational wealth that easily withstands inflationary pressures.
Long-Term Wealth Architecture & Behavioral Principles
Sustainable personal wealth is the predictable reward of consistent behavioral discipline executed over decades. By separating emotional desires from cash flow allocation, funding liquid emergency buffers, and maintaining automated broad-market equity investments, households build true financial autonomy.
Regularly auditing household expenses and maintaining low-cost, diversified asset allocation models via institutions like Vanguard and Fidelity ensures that your wealth compounds steadily across all economic cycles.
Frequently Asked Questions (FAQ)
Is Google Sheets or Microsoft Excel better for personal budgeting?
Google Sheets is generally superior for household budgeting because it offers real-time cloud synchronization across mobile devices, seamless collaboration with a spouse, and built-in live financial data formulas.
How can one enter transactions without manual typing friction?
Most online banking portals allow you to export monthly transactions directly as a CSV file. You can paste the raw CSV data into your transaction tab in under 30 seconds to update your entire workbook instantly.
How do I set up visual spending alerts in a budget spreadsheet?
Use Conditional Formatting: configure cells to turn green when actual spending is under 90% of budget, yellow between 90% and 100%, and red when spending exceeds the budgeted ceiling.
How can sinking funds be modeled inside a spreadsheet?
Create a dedicated column calculating (Target Amount - Current Balance) / Remaining Months to automatically compute the required monthly savings transfer for each upcoming annual expense.
Strategic Conclusion and Next Steps
A custom monthly budget spreadsheet gives you complete clarity and sovereign control over your personal financial trajectory. By tracking transactions, automating categorical summaries, and updating your net worth balance sheet monthly, you build an enduring system for lifetime wealth accumulation.
Create your spreadsheet workbook today: set up your four core worksheets, populate your fixed baseline expenses, and begin logging daily transactions to achieve total financial clarity.